Last updated: November 18, 2026
Key Takeaways
- Budget progress means the plan is working even when income changes.
- A useful tracking system uses one income journal, one monthly summary, and one comparison view.
- Compare months with ratios, category patterns, and cash-flow timing rather than raw totals alone.
- Watch which categories drift first, because early drift often shows the weakest budget line.
Quick Answer
Track budget progress by measuring each month’s income, spending, and leftover cash against the same categories, then compare patterns over time. For a variable-income budget, the clearest signal is whether essentials stay covered and month-end cash still makes sense.
If your income changes month to month, track budget progress against your budget progress tracking system instead of against one fixed dollar target. Measure how much of each month’s income was assigned, saved, spent, and left over, then compare those ratios and category totals across months. This article on How to Track Budget Progress When Income Changes Month to Month shows how to do that without forcing every month into the same dollar amount.
What budget progress means when income is uneven
Budget progress means your plan is doing the job you asked it to do, even when the paycheck amount shifts. On a steady salary, progress can look like “I stayed within the plan.” With variable income, that standard breaks fast. A $3,200 month and a $5,100 month need different expectations, or your numbers will lie to you.
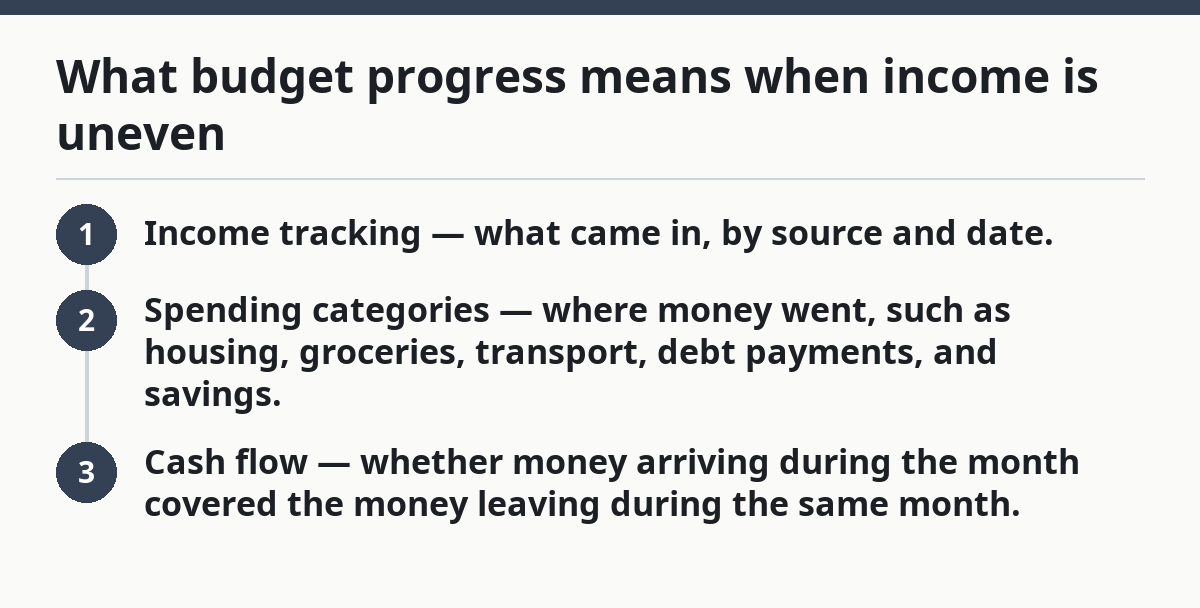
The simplest way to think about progress is in three layers:
- Income tracking — what came in, by source and date.
- Spending categories — where money went, such as housing, groceries, transport, debt payments, and savings.
- Cash flow — whether money arriving during the month covered the money leaving during the same month.
That means the question is not “Did I hit every planned dollar exactly?” It is “Did I protect the priorities I meant to protect, and did I finish the month with the right amount left over for the next step?”
A good system also separates planned, actual, and adjusted numbers. Planned is the starting budget. Actual is what happened. Adjusted is the revision you made after the month changed. Those three columns matter more than a single yes-or-no answer. If a budget category was over by $40 but another category stayed under by $75, the month may still be healthy.
This approach is not for someone who wants a perfectly fixed monthly target with no revisions. That method creates false failures when income is irregular. It is also not a fit if you only want a “spend less” rule. The point here is tracking progress, not squeezing every month into the same box.
How to set up the budget progress tracking system
A budget progress tracking system works best when it has one income journal, one monthly summary, and one comparison view. You do not need a complicated app to do this. A spreadsheet with 3 tabs is enough. So is a notebook with a 2-page spread per month.
Start with these fields:
- Month
- Income source
- Income amount
- Date received
- Spending category
- Planned amount
- Actual amount
- Difference
- Notes on budget adjustments
The budget journal is where you write the decision behind the number, not just the number itself. If you dipped into grocery money to cover a car repair, write that down. If you delayed a savings transfer because income came in late, write that down too. Those notes explain the month when you review it later.
Use the same category names every month. If one month says “food,” the next says “groceries,” and the next says “household,” comparison gets muddy. Pick a small list and keep it stable. Common categories include rent or mortgage, utilities, groceries, gas or transit, debt minimums, child costs, insurance, savings, and irregular expenses.
For cash flow, record the date income arrives. A month with two payments on the 5th and 20th behaves differently from a month with one payment on the 28th. The timing matters because a budget can look fine on paper and still fail in the middle of the month if bills hit before cash arrives.
The cleanest setup is monthly totals plus weekly check-ins. Even one 10-minute review each week can stop a small category problem from turning into a month-end surprise. If that sounds too detailed, cut the system down, but keep the same structure every month. Consistency matters more than complexity.
If you want a reference point for structure, the basic budgeting and spending categories used in many personal finance systems can be aligned with consumer guidance from the Consumer Financial Protection Bureau and the National Endowment for Financial Education; the exact format can still be simple and personal.
How do I compare months when income changes?
You compare months by ratios, category patterns, and cash-flow timing, not by raw totals alone. Raw totals are useful, but they do not tell the full story when one month is 30% higher than another.
Use this core procedure each month:
- Record every income deposit for the month. Put each payment in the same place, with the date and source, so you can see the month’s actual income pattern instead of relying on memory.
- Add up monthly total income. Use the total as your comparison base. If the month brought in $4,000, every category can be read against that number rather than against last month’s $3,100.
- Calculate each category as a share of income. If groceries were $600 in a $4,000 month, they used 15% of income in that example. That percentage is easier to compare than the dollar amount alone.
- Mark any mid-month changes in a budget journal. Write the reason for each adjustment, such as a delayed invoice, overtime pay, or a larger-than-expected utility bill. Those notes explain why one month behaved differently.
- Compare the same category across at least 3 months. Three data points show a pattern better than one month does. You may see, for example, that transport can rise in months with more driving.
- Check month-end cash left after priorities. After fixed bills, minimum debt payments, and planned savings, look at what remained. That leftover cash shows whether the month supported the next one.
The comparison should answer one question: did the month move you toward stability, or did it require too many emergency moves?
Month-over-month comparison works best when you pair it with one baseline month. Pick a typical month, not your best month and not your worst. Then track how later months differ from it. If your income moves a lot, this keeps you from judging every month against an unrealistic high point.
A practical check is to compare fixed-cost coverage first. If rent, utilities, insurance, and minimum debt payments consume most of the income in a low month, the budget may still be fine if the essentials were covered. If those same costs crowd out groceries or transportation, the system needs a reset.
What should I watch in spending categories, not just totals?
You should watch which categories drift first, because the first drift usually tells you where the budget is weakest. Totals can hide a lot. A month can look balanced while groceries, transport, and small subscriptions quietly climb.
Start with categories that move when income changes:
- Groceries and household items often flex because they are paid several times in a month.
- Transportation shifts with work hours, commuting distance, and fuel use.
- Dining out and convenience spending tends to rise when time is tight.
- Irregular bills like annual renewals, school costs, or car maintenance can break a month if they are not set aside in advance.
A useful test is to ask whether a category changed because of a real need or because the month felt tight. Those are not the same. If income dropped and takeout went up, the spending pattern may be reacting to stress, not need.
Watch for category creep. That happens when one category covers expenses it was never meant to hold. If “miscellaneous” keeps swallowing recurring costs, the budget stops teaching you anything. Split the category or rename it. A budget category should describe a behavior, not hide one.
The honest trade-off here is that tighter tracking can feel repetitive. You may be tempted to stop labeling small purchases once the month gets busy. That saves time and costs insight. A stack of unnamed $8 charges tells you nothing by the end of the month. Three labeled $8 charges can show a pattern.
Also watch for over-correction. If income rises one month, it is easy to relax the category limits and call it progress. A higher-income month is progress only if the extra money got assigned on purpose — to savings, debt, or future irregular bills — instead of leaking into every category by default.
How to read trend tracking without fooling yourself
Trend tracking works when you look for repeated behavior over 3 to 6 months, not one lucky month. One good month can be a fluke. Three similar months usually mean something real.
The main trend questions are simple:
- Is the same category overspending every month?
- Does a certain type of month sometimes create a cash shortage?
- Are you saving the same percentage of income, or only saving when income is unusually high?
- Do budget adjustments happen early in the month or only after money is already gone?
This is where a budget progress tracking system earns its keep. A raw ledger tells you what happened. Trend tracking tells you what keeps happening.
A strong trend note sounds like this: “When income arrives after the 20th, groceries and gas get overused by the second week.” That note is useful because it names timing, not just spending. Another useful note is: “Months with two payments allow savings transfers to happen on time; one-payment months do not.” That is a cash-flow pattern, not a moral failure.
Use simple markers in your monthly totals, such as:
- Green for categories under plan
- Yellow for categories within about 5% to 10% of plan
- Red for categories over plan or requiring a transfer
You do not need exact color codes to the penny. You need enough contrast to spot the categories that repeat. If a category is red 4 months in a row, the budget line is probably too low or the habit is too costly. If a category turns red only in months with a late payment, the problem may be timing, not spending.
The thing a generic budget article often misses is that trend tracking is not punishment. It is diagnosis. If you turn every overage into a failure, you will stop reviewing the data honestly. If you treat the same overage as information, you can adjust the plan without rebuilding it from scratch, but if the changes keep piling up or affect debt, taxes, or savings goals, consult a qualified financial professional and use guidance from the Consumer Financial Protection Bureau or the National Endowment for Financial Education.
How to adjust the budget without losing the thread
You adjust the budget by changing the plan on paper, not by pretending the old plan still fits. When income changes month to month, the goal is not to preserve the original budget at all costs. The goal is to preserve direction.
Make adjustments in this order:
- Protect the essentials first. Keep housing, utilities, food, transport, insurance, and minimum debt payments covered.
- Reduce flexible categories next. Slow down dining out, entertainment, and non-urgent shopping before cutting essentials.
- Update savings in proportion to income. If your income drops, a flat savings goal may be unrealistic for that month. Record the change and restore it later when income improves.
- Write the adjustment note. Note the reason, the date, and what changed.
- Review the month-end result. Decide whether the adjustment fixed a timing issue or only delayed a shortfall.
The adjustment note matters because it keeps the story intact. Without it, next month’s review becomes guesswork. A note such as “moved $80 from household to gas after extra work commute” explains the budget in one line. That makes future month-over-month comparison possible.
Be careful not to use adjustments as camouflage. Moving money around once is smart. Moving money around every week because the original numbers were unrealistic means the plan itself needs repair. That is a useful conclusion, not a failure.
A common mistake is to judge progress only by whether every category stayed within its original cap. With variable income, that standard can be misleading. A better measure is whether the essential bills were paid, the month-end cash position made sense, and the budget notes explain the differences clearly.
If you keep the same categories, the same monthly totals, and the same adjustment notes, you can see real progress even when income shifts. That is the point. The plan becomes a record of decisions, not a scorecard that punishes normal variation.
The guide to single-parent budget foundations fits well with this approach because it treats budgeting as an ongoing process, not a one-time setup; for household-specific decisions, consult a qualified financial professional and compare the plan with Consumer Financial Protection Bureau guidance.
How do I know if my budget is working?
Your budget is working if it covers the essentials, keeps cash flow understandable, and shows a repeatable pattern in your monthly totals. It does not need to look perfect. If you can explain why each major category changed and you are not surprised at month end, the system is doing its job.
What should I track each month?
Track total income, category totals, savings transfers, minimum debt payments, and any budget adjustment notes. Those five pieces show both the money you had and the choices you made with it. A budget journal also helps when the month changes after you made the original plan.
How do I compare months when income changes?
Compare months using percentages of income, not just dollar amounts. Then look at the same spending categories across at least 3 months and check whether the same timing problems keep showing up. That tells you whether the budget needs a small adjustment or a deeper reset.
Drafted with AI; not yet reviewed by a person.